
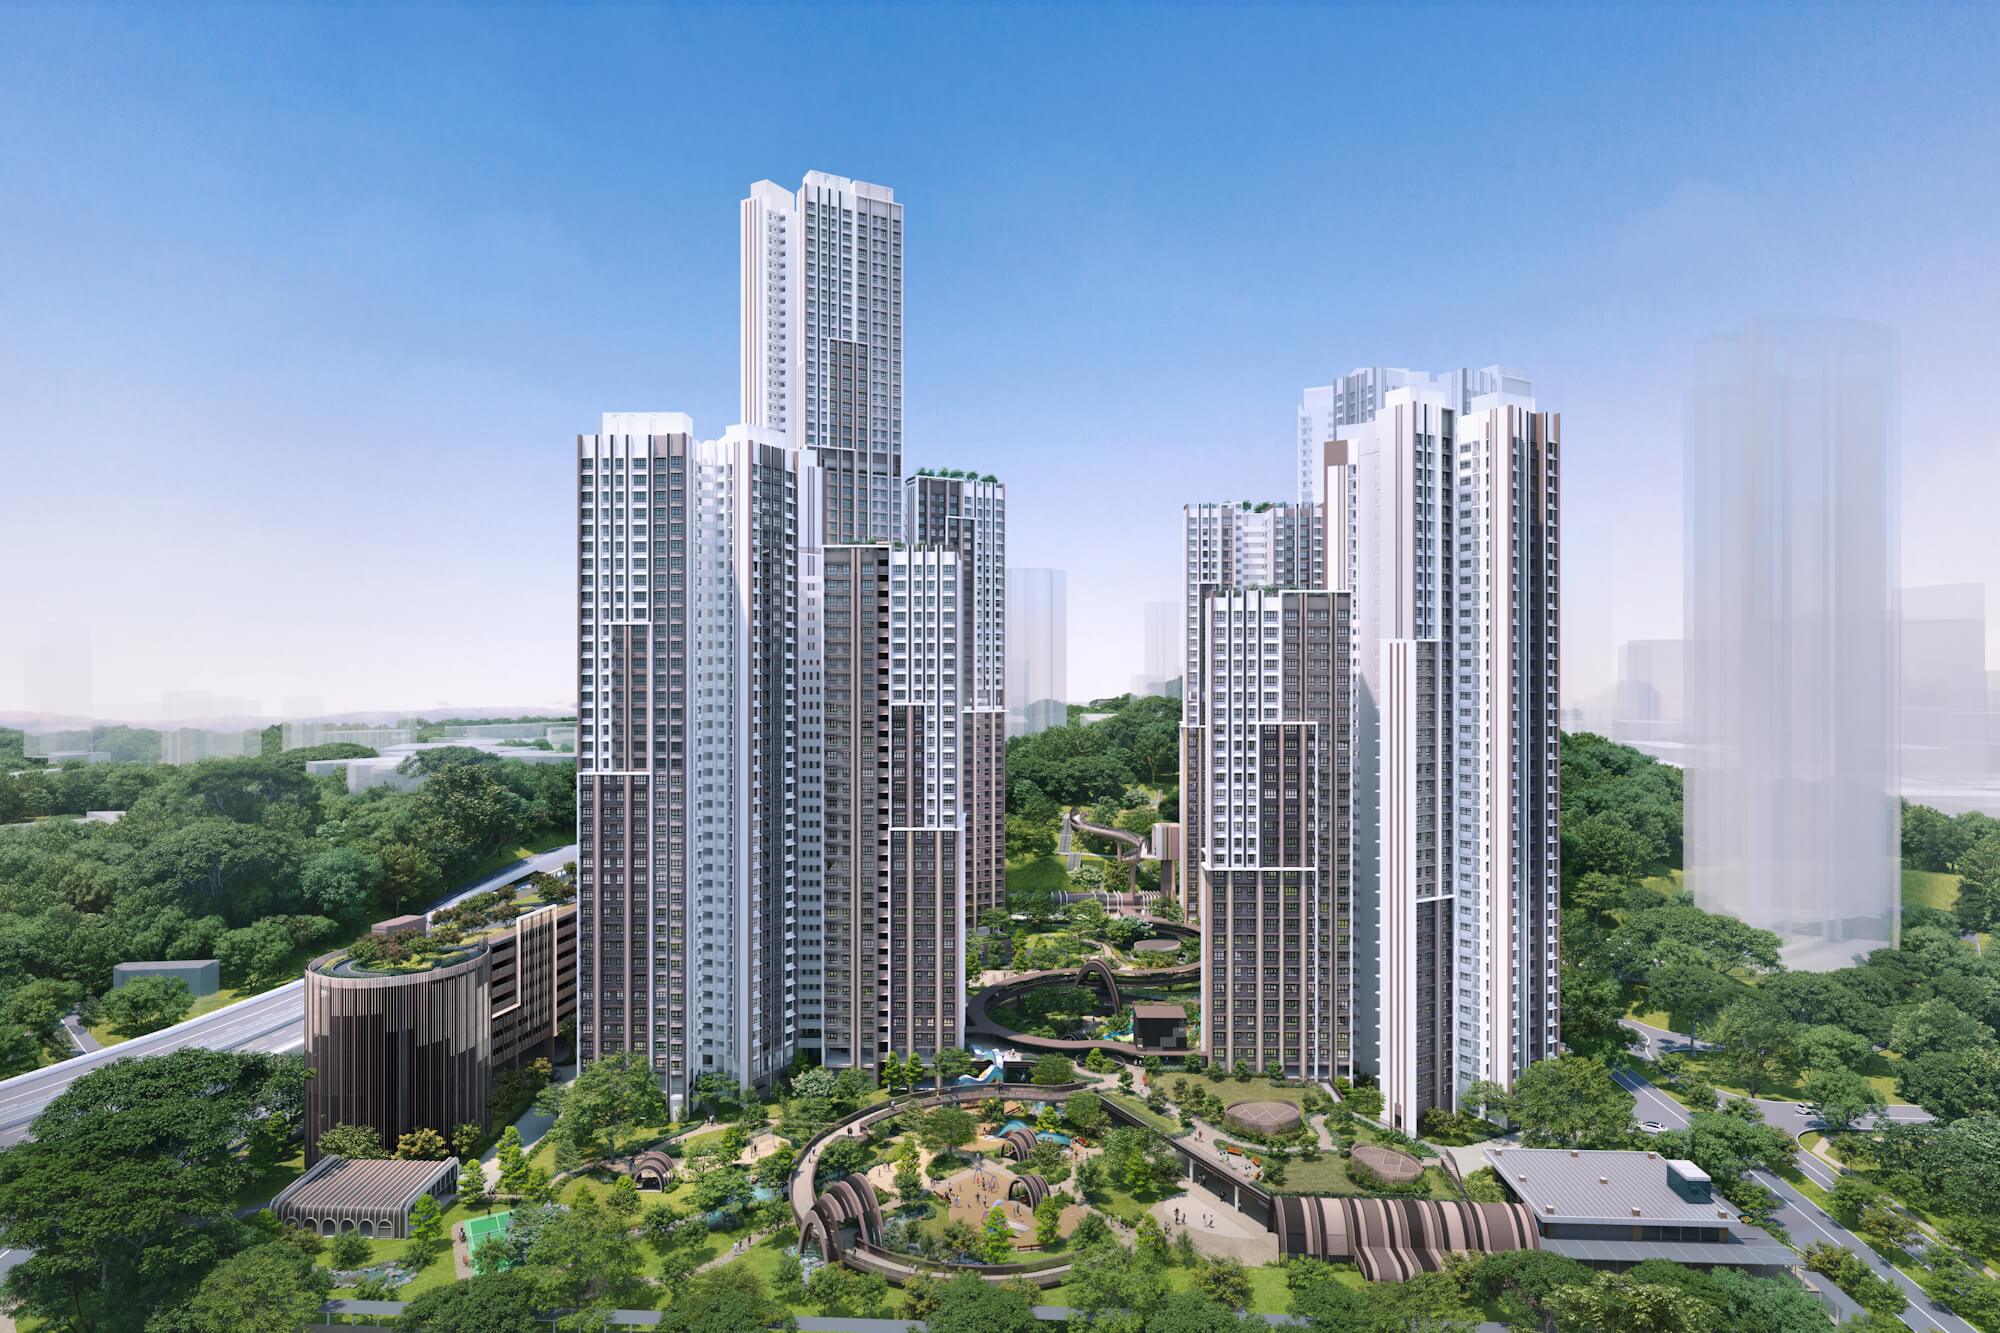
Housing & Development Board (HDB) flats can be bought as Build-to-Order (BTO) flats directly from HDB, or as resale flats from other homeowners.
Eligible buyers of both BTO flats and resale flats receive CPF housing grants to help with their flat purchase. However, BTO flats enjoy significant market discounts via government subsidies to ensure affordability. These make them significantly cheaper than resale flats. We recently ran the numbers and found that the median monthly household income required to buy a 3- to 5-room resale HDB flat ranges from $5,872 to $9,712.
In this article, we look at how much a couple would need to earn to afford different BTO flat types after accounting for government subsidies.
Read Also: 5 HDB BTO Application Tips For Young Singaporean Couples To Get Their Homes
Assumptions For Our Calculations
The following calculations are only meant as a guide and would differ depending on individual circumstances. Consider speaking to a trusted home loan broker before committing to a home purchase and loan.
Here are the assumptions used throughout this article:
- The couple do not have any other loans or financial commitments that would affect their Total Debt Servicing Ratio (TDSR) and Mortgage Servicing Ratio (MSR).
- The couple has sufficient cash and/or CPF Ordinary Account (OA) savings for the downpayment, i.e. 25% of the purchase price of the HDB BTO flat.
- The couple is utilising the maximum 25-year home loan tenure.
- Interest rate for the home loan is 2.6% for HDB flats (i.e. the current HDB loan rate). Mortgage payments are calculated using CPF’s Mortgage Calculator.
- Estimated household income required is obtained using the Reverse Affordability Calculator provided by Cashew, as a reference. We estimate income using a 4% illustrative stress rate and a 30% Mortgage Servicing Ratio. HDB assesses its own loans separately.
- The couple meets the eligibility criteria for the maximum government grants for our income
- All costs mentioned exclude Stamp Duty, lawyer fees, renovation or other miscellaneous expenses.
Salary Needed To Afford An HDB BTO Flat (By Flat Size And Classification)
The introduction of the new HDB flat classification in 2024 categorised BTO launches into Standard, Plus, and Prime. BTO projects are classified by their location, based on their connectivity and proximity to the city centre, as well as surrounding amenities. The more attractive a location, the higher the subsidies, ensuring flats across the island remain affordable for a wide range of buyers, regardless of location.
We use the highest starting price for each flat type and classification in HDB’s November 2026 BTO exercise, before grants. For 2-room flats, we used the highest starting price for a 99-year lease. Individual units may cost more.
| Price | Minimum Downpayment | Monthly Repayments | Monthly Household Income | |
| Standard | ||||
| 2-room | $156,000 | $39,000 | $531 | $2,059 |
| 3-room | $297,000 | $74,250 | $1,011 | $3,920 |
| 4-room | $353,000 | $88,250 | $1,201 | $4,659 |
| 5-room | $494,000 | $123,500 | $1,681 | $6,519 |
| 3Gen | $551,000 | $137,750 | $1,875 | $7,271 |
| Plus | ||||
| 2-room | $253,000 | $63,250 | $861 | $3,339 |
| 3-room | $409,000 | $102,250 | $1,392 | $5,398 |
| 4-room | $559,000 | $139,750 | $1,902 | $7,377 |
| Prime | ||||
| 2-room | $243,000 | $60,750 | $827 | $3,207 |
| 3-room | Not offered | — | — | — |
| 4-room | $558,000 | $139,500 | $1,899 | $7,364 |
These are the salaries required to purchase a subsidised BTO flat directly from HDB, excluding the additional housing grant.
Salary Needed To Afford Buying A BTO Flat With Enhanced CPF Housing Grant (EHG)
First-time BTO buyers can apply for the Enhanced CPF Housing Grant (EHG) to help with their purchase of the new flat. From 20 August 2024, first-timer families may qualify for an EHG of up to $120,000, while a couple comprising a first-timer and second-timer may qualify for an EHG (Singles) of up to $60,000.
Homebuyers can use the grant to either offset the purchase price of the flat or reduce their mortgage loan, but they cannot use it for the minimum cash downpayment (if any) or for monthly mortgage instalment payments.
Note: Buyers taking an HDB loan may use eligible CPF savings for their downpayment. The amount they need upfront depends on their approved loan and available CPF savings.
For these illustrations, we subtract the EHG from the price and assume the buyer borrows 75% of the remaining amount. The buyer funds the other 25% with cash and/or CPF savings. Each row shows the lowest gross monthly household income that meets the 30% repayment threshold at 4%, using the grant tier for that same income. The grant is subject to HDB’s eligibility rules and income assessment.
| Price | EHG | Price After EHG | Monthly Household Income | |
| Standard | ||||
| 2-room | $156,000 | $120,000 | $36,000 | $476 |
| 3-room | $297,000 | $95,000 | $202,000 | $2,666 |
| 4-room | $353,000 | $90,000 | $263,000 | $3,471 |
| 5-room | $494,000 | $50,000 | $444,000 | $5,859 |
| 3Gen | $551,000 | $30,000 | $521,000 | $6,876 |
| Plus | ||||
| 2-room | $253,000 | $110,000 | $143,000 | $1,888 |
| 3-room | $409,000 | $70,000 | $339,000 | $4,474 |
| 4-room | $559,000 | $30,000 | $529,000 | $6,981 |
| Prime | ||||
| 2-room | $243,000 | $110,000 | $133,000 | $1,756 |
| 3-room | Not offered | — | — | — |
| 4-room | $558,000 | $30,000 | $528,000 | $6,968 |
As seen in the tables above, the Enhanced CPF Housing Grant (EHG) can make a substantial difference in the prices of BTO flats, especially for the smaller sized flats and the minimum salaries required to afford them.
Read Also: Here’s What Happens When You Give Up Your HDB BTO Queue Number
Buy Within Your Means Based On Your Needs
While the EHG is meant to help first-time homebuyers, it may also encourage some to purchase beyond their means. This could be buying large flat types (i.e, 5-room), when their household size is small, or considering more expensive locations, which might be out of their budget if not for the EHG to help with their downpayment.
One way to be more prudent is to exclude the EHG from our considerations and instead focus only on our housing needs and affordability level when selecting our BTO. This way, the EHG will complement our ability to finance the property rather than stretch our finances.
Advertiser Message
What If You Could Get A Year’s Rent Upfront?
With LyteLease, landlords can receive up to 12 months of rental income upfront. You pay a one-time flat fee, with no interest, and LyteLease handles rent collection for you.



Branded Content
Why Your Investing Journey Works Better With A Buddy


