

After rising sharply in 2022 and 2023, home loan interest rates in Singapore have fallen considerably from their previous highs. This has provided some relief for homeowners, particularly those who have refinanced their mortgages or switched to more competitive home loan packages.
However, the interest rate outlook may be changing again.
On 16 September 2026, the US Federal Reserve announced a 0.25 percentage point interest rate hike, raising its benchmark rate to 3.75%–4.00%. This marked its first rate increase since July 2023, following a series of interest rate cuts that began in September 2024.
While an increase in US interest rates does not automatically translate into higher mortgage rates in Singapore, it raises the possibility that borrowing costs here could increase. For homeowners with floating-rate mortgages, even a 1% increase in interest rates could mean paying hundreds of dollars more each month.
Home Loan Interest Rates In Singapore Have Fallen From Their Previous Highs
Before 2022, many homeowners were accustomed to home loan interest rates below 1.5%. This changed when global interest rates rose sharply, with mortgage rates in Singapore exceeding 3% during the higher-interest-rate environment.
Since then, borrowing costs have eased considerably. As of September 2026, the three-month compounded Singapore Overnight Rate Average (SORA), a benchmark widely used for floating-rate home loans, was approximately 1.2%. This is significantly lower than the levels exceeding 3% seen during the previous interest rate hike cycle.
For homeowners with floating-rate mortgages, lower SORA rates generally translate into lower borrowing costs when their mortgage interest rates reset. However, the actual interest rate we pay depends on the bank’s spread and the terms of our home loan package.
For example, a floating-rate mortgage priced at three-month compounded SORA + 0.50% would have an effective interest rate of approximately 1.7% if the applicable SORA rate were 1.2%.
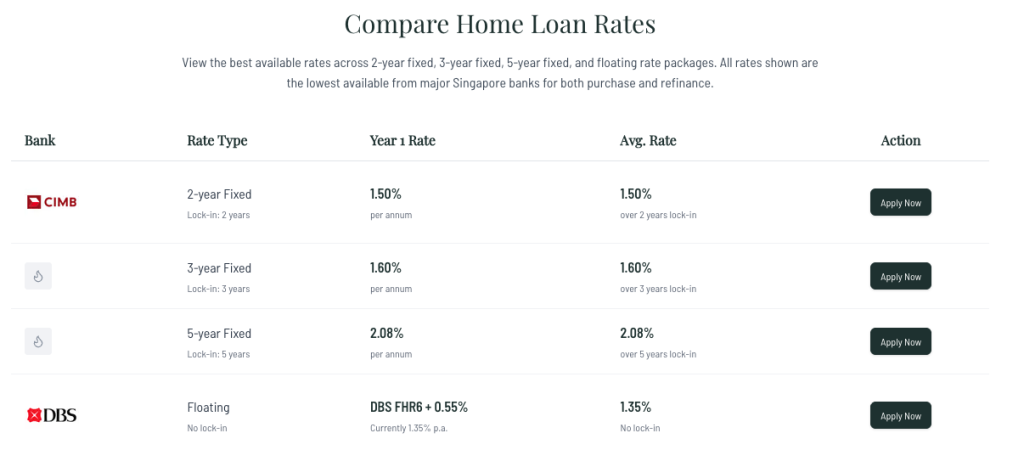
Fixed-rate home loan packages have also become more competitive. As of September 2026, some advertised fixed-rate packages were available from around 1.5% to 1.7% per annum, although the actual rates offered depend on factors such as the loan amount, property type and mortgage package.
Source: Cashew
How Does A 1% Increase In Interest Rates Affect Our Home Loan Repayments?
While mortgage rates in Singapore remain well below their previous highs, the Federal Reserve’s latest rate hike reminds us that borrowing costs can rise again. A home loan typically stretches over 20 to 30 years, during which interest rates can change considerably.
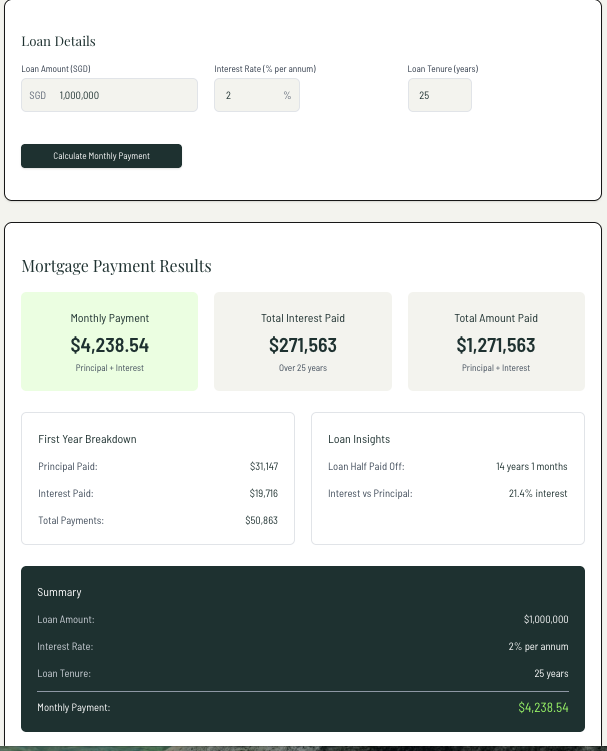
Let’s assume we buy a $1.35 million private property and take a bank loan of about $1 million, or roughly 75% of the purchase price. For simplicity, we will use a $1 million mortgage with a 25-year repayment tenure to illustrate how different interest rates affect our monthly repayments.
Source: Cashew
At an interest rate of 2%, our monthly mortgage repayment would be approximately $4,239. If the interest rate increases to 3%, our monthly repayment would rise to $4,742, an increase of about $503 a month or $6,036 a year.
| Home Loan Interest Rate | Monthly Repayment | Annual Repayment |
| 2.0% | $4,239 | $50,868 |
| 3.0% | $4,742 | $56,904 |
| 4.0% | $5,278 | $63,336 |
| 5.0% | $5,846 | $70,152 |
The difference becomes even more significant at higher interest rates. At 4%, our monthly repayment would increase to approximately $5,278, while a 5% interest rate would push it to about $5,846. This means that a homeowner paying 2% interest on a $1 million mortgage could face more than $1,000 in additional monthly repayments if interest rates increase to 4%.
A simple rule-of-thumb way to think about it would be that for a $1 million loan, an increase of 1% in the interest rate will cost you about $500 a month (assuming a 25-year repayment period).
Fixed Or Floating Home Loan: Which Should We Choose?
For homeowners taking a new mortgage or refinancing an existing one, an important consideration is whether to choose a fixed-rate or floating-rate home loan.
A fixed-rate mortgage provides certainty over monthly repayments during the fixed-rate period, commonly two or three years. A floating-rate mortgage typically follows a benchmark such as the one-month or three-month compounded SORA, plus a spread charged by the bank. This allows us to benefit when market interest rates decline, but our monthly repayments may also increase when interest rates rise.
With the Federal Reserve raising interest rates again, homeowners considering floating-rate mortgages should be mindful that SORA could also rise. However, this does not necessarily mean fixed-rate packages will always be cheaper, as banks may already have factored expectations of future interest rate movements into their mortgage pricing.
Read Also: Interest Rates Are Going Up. Should I Be Refinancing My Mortgage As Soon As Possible?
Should We Refinance Our Home Loan When Interest Rates Change?
For homeowners who secured their mortgages during the higher-interest-rate environment of 2023 or 2024, refinancing or repricing could help reduce monthly repayments if their existing interest rates are higher than the packages currently available.
Repricing involves switching to another home loan package offered by our existing bank, while refinancing involves moving our mortgage to another financial institution. Both options may help us secure a more competitive interest rate, although refinancing typically involves additional legal and administrative costs.
Before switching, we should check whether our existing mortgage is still within its lock-in period and whether early repayment penalties, legal fees or subsidy clawbacks apply. These costs could offset the savings from a lower interest rate, particularly if we intend to sell our property in the near future.
For example, reducing the interest rate on a $1 million mortgage with 25 years remaining from 3% to 2% would lower monthly repayments by approximately $503, or more than $6,000 a year. However, actual savings depend on our outstanding loan amount, remaining tenure, and refinancing costs.
Homeowners can use mortgage comparison services such as Redbrick and Cashew to compare available home loan packages and assess whether refinancing or repricing makes financial sense.
Read Also: Why Knowing All About Home Loan Rates Still Cost Me More Than An HDB Loan
This article contains affiliate links. DollarsAndSense may receive a share of the revenue from your sign-ups. You can refer to our editorial policy here.


