

As a government scheme ensuring Singaporeans with retirement adequacy, Central Provident Fund (CPF) is also a tool that Singaporeans can use to maximise their savings for retirement. Based on the CPF accounts, we can receive a base interest rate of 2.5% for Ordinary Account (OA) and 4% for Special Account (SA) and Retirement Account (RA).
Under the Retirement Sum Topping-Up Scheme (RSTU), we can use cash or CPF transfers to build our own or another CPF member’s retirement savings, subject to the scheme’s eligibility rules. This guide focuses on cash top-ups. The money goes into the recipient’s Special Account (SA) if they are below 55. From age 55, when the SA closes, cash top-ups go into the Retirement Account (RA).
Read Also: Complete Guide To CPF Retirement Account
There are two main benefits to topping up with cash via RSTU. First, by topping up early, we give our savings more time to compound at the prevailing SA and RA base rate of 4% per annum. Cash top-ups start earning interest the month after they are received.
Second, eligible cash top-ups can give us up to $8,000 in tax relief for ourselves and another $8,000 in total for eligible family members each calendar year. Eligible MediSave top-ups share these limits, and the overall personal income tax relief cap is $80,000. For a spouse or sibling without a disability, their annual income in the year before the top-up must be $8,000 or less. The portion of a cash top-up that attracts a Matched Retirement Savings Scheme grant does not qualify for tax relief.
Before topping up, it is important to note that the process is irreversible. Therefore, do make sure the RSTU cash top-up scheme is aligned with your overall cash flow and retirement strategy.
Read Also: Retirement Sum Topping-Up Scheme (RSTU) VS CPF Voluntary Contributions: What’s The Difference?
#1 Open CPF Board’s Retirement Top-Up Form
Open the Cash Top-Ups and CPF Transfers for Retirement form. Read the Terms of Use and then click Start.
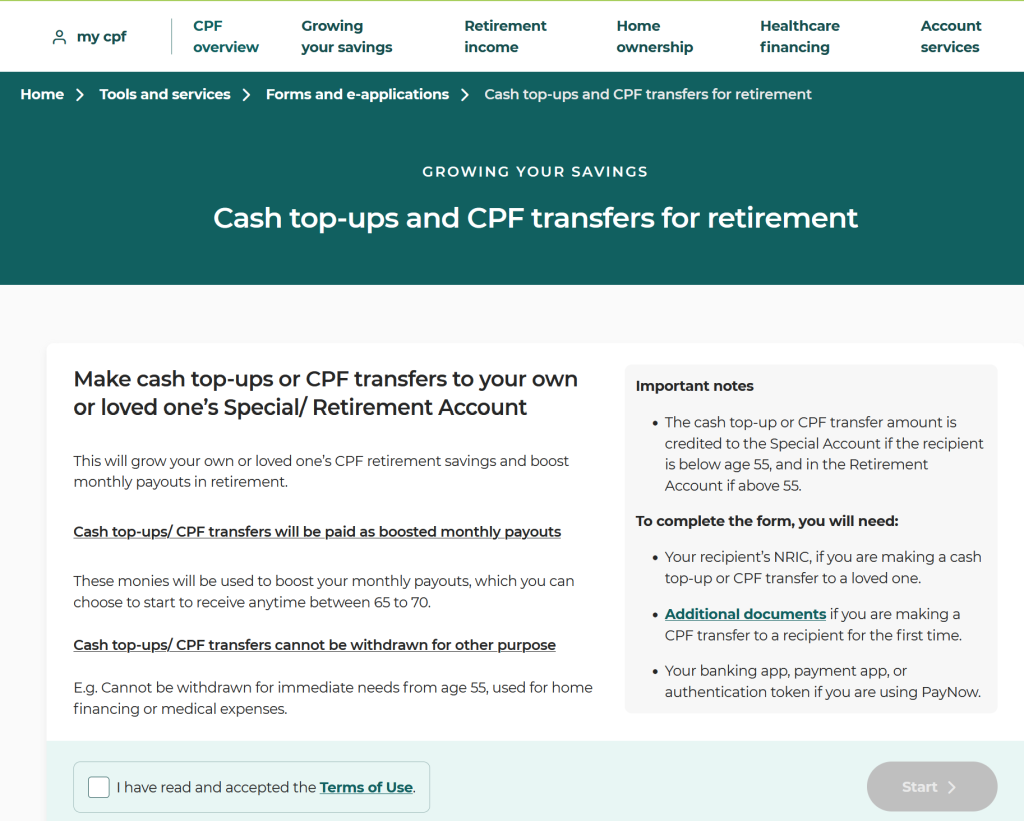
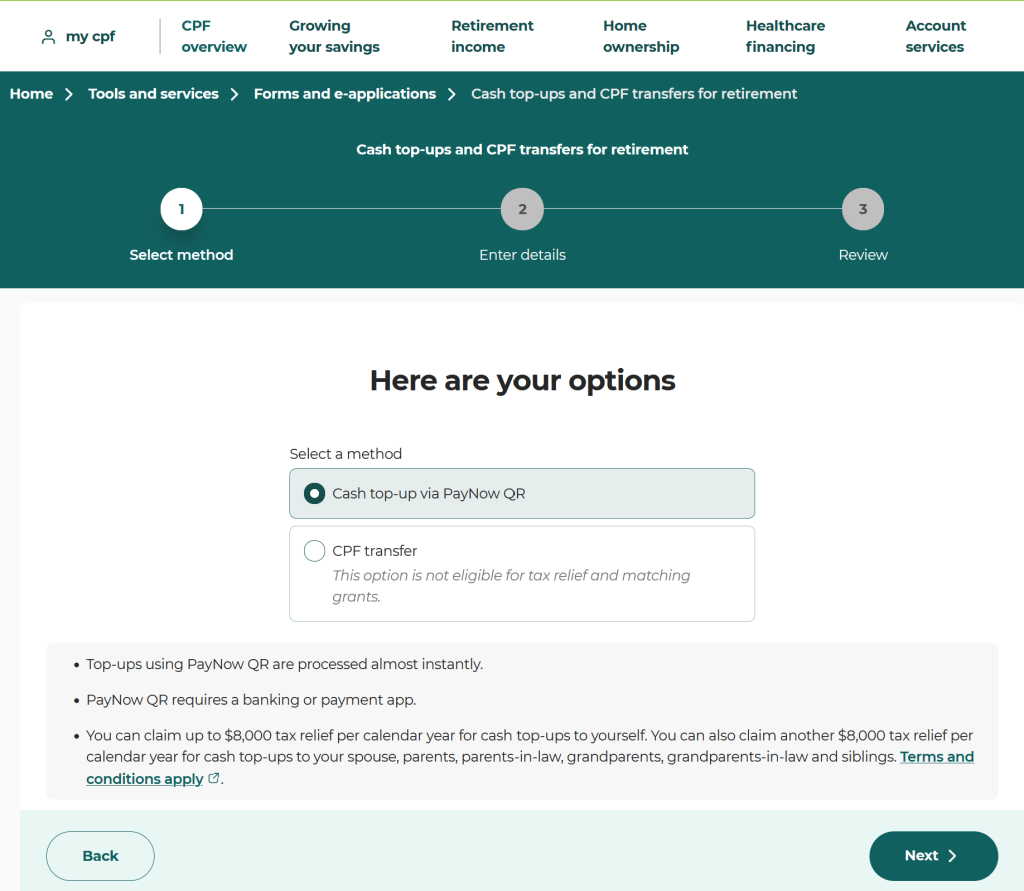
#2 Select Cash Top-Up And Choose The Recipient
Select Cash top-up via PayNow QR and click Next.
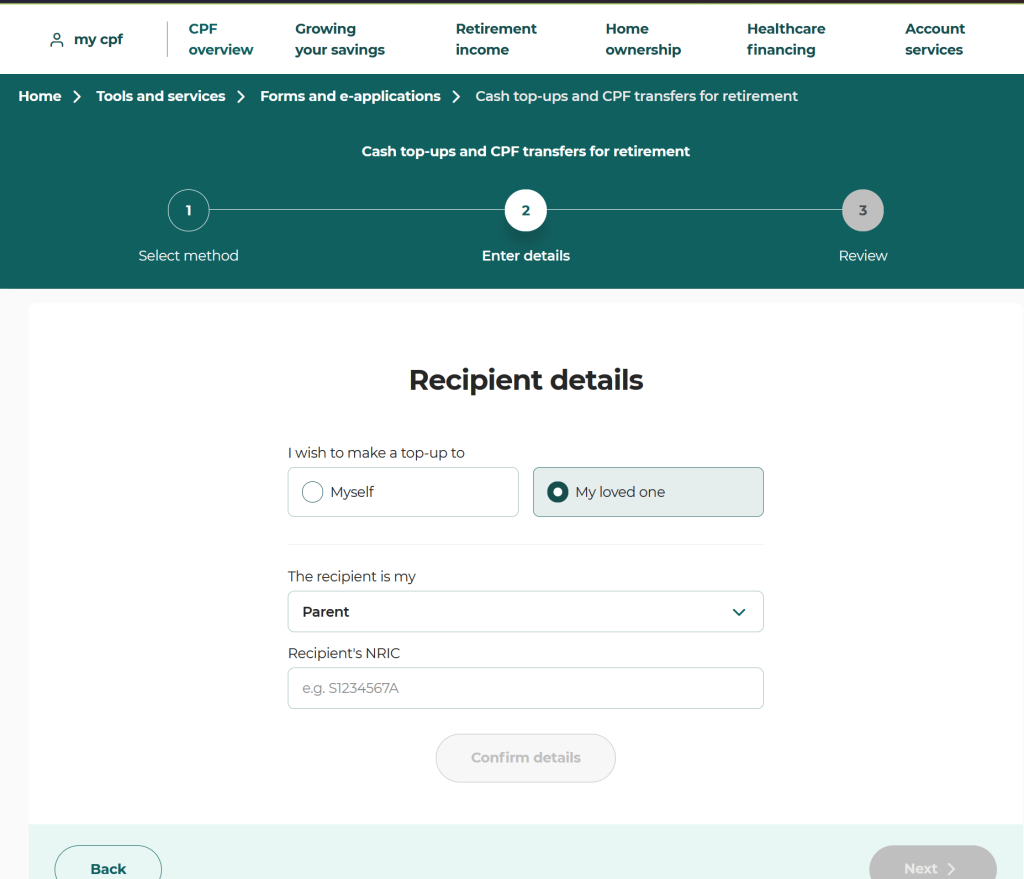
Choose Self if you are topping up your own CPF account. If you are topping up for someone else, select the recipient’s relationship to you and enter their NRIC.
Read Also: BRS, FRS, ERS: Why There Are 3 CPF Retirement Sums & Why They Increase Every Year
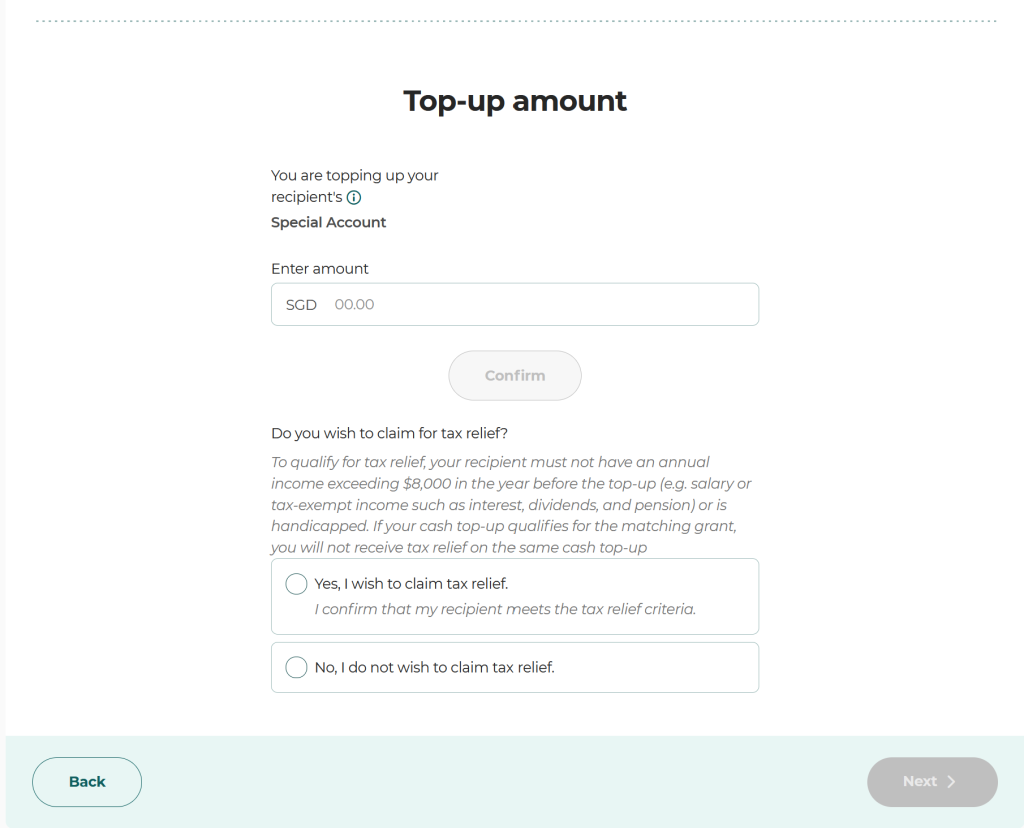
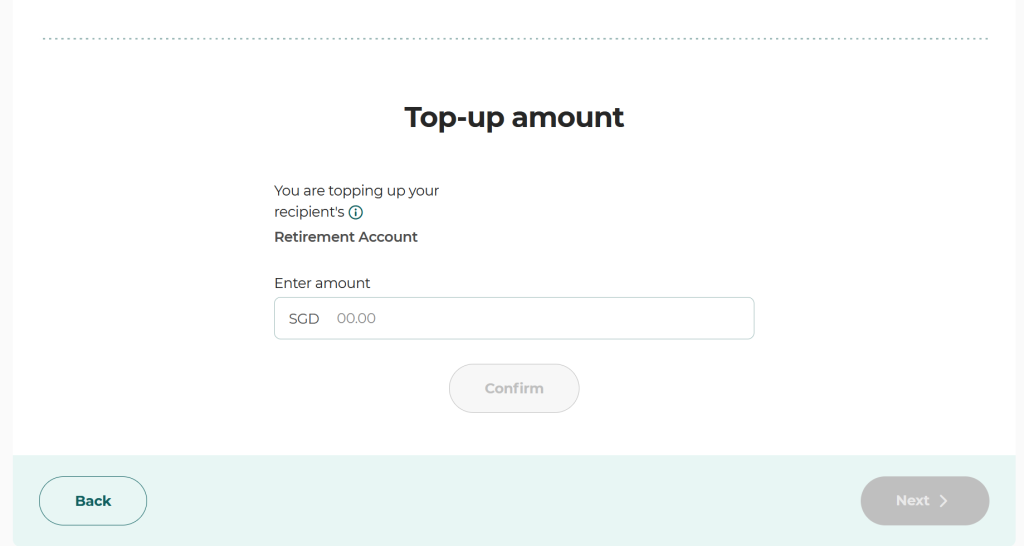
#3 Enter The Top-Up Amount
For recipients below 55, the 2026 top-up limit is the prevailing Full Retirement Sum (FRS) of $220,400, less their SA savings and net SA savings still invested under the CPF Investment Scheme. From age 55, recipients can top up their RA to the prevailing Enhanced Retirement Sum (ERS), which is $440,800 in 2026. Tax relief on eligible retirement cash top-ups is calculated using the prevailing FRS for both age groups. Check your CPF Retirement Dashboard for your personal top-up limit.
Read Also: Pros And Cons Of Making RSTU Top-Ups To Your CPF Account At The Start Of The Year
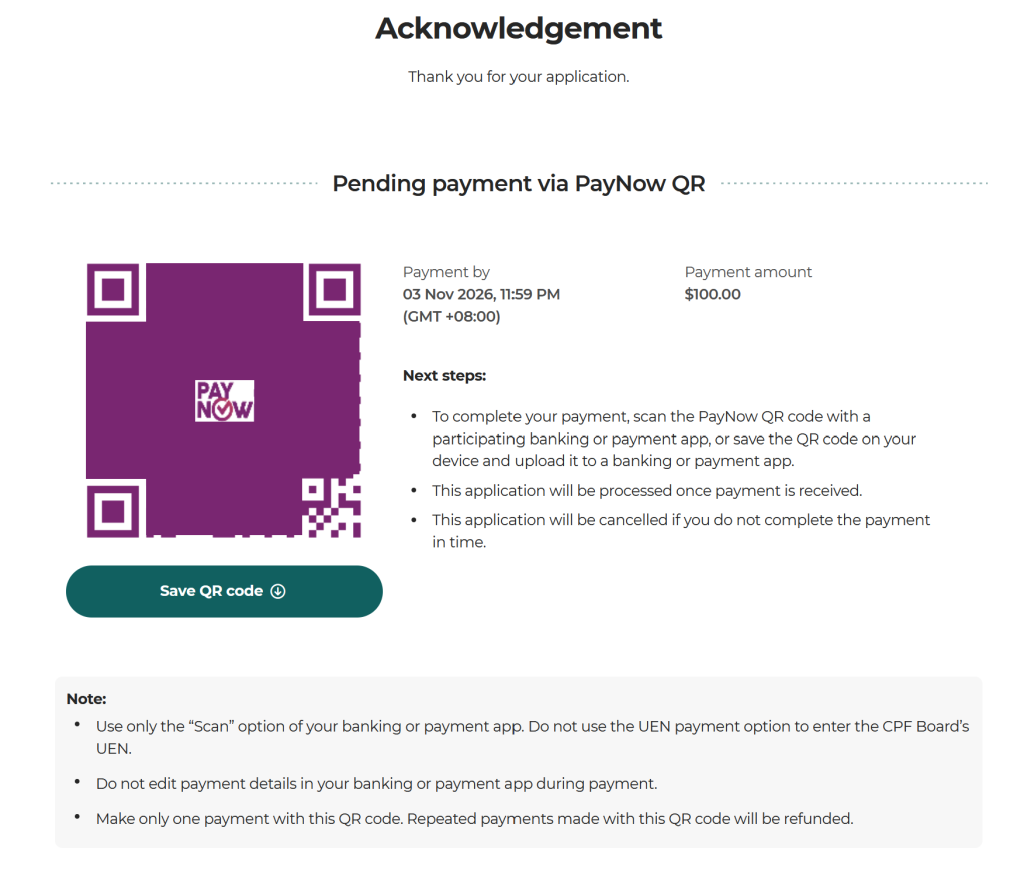
#4 Review The Application, Complete Payment And Save The Confirmation
Review the recipient and top-up amount before paying via PayNow QR. Keep the payment confirmation for your records. The cash top-up is reserved for retirement payouts.
Read Also: CPF Top-Ups VS SRS Top-Ups: Which Should You Choose?


