
This article is written in collaboration with CIMB Singapore. All views expressed in this article are the independent opinion of DollarsAndSense.sg based on our research, and is purely for informational purposes and should not be relied upon as financial advice. DollarsAndSense.sg is not liable for any financial losses that may arise from any transactions and readers are encouraged to do their own due diligence. You can view our full editorial policy.
In Singapore, running a small- or medium-sized enterprise (SME) comes with its own set of challenges. Besides worrying about their business growth, most SME owners spend a significant amount of time thinking about revenue, costs and cash flow. However, fewer may spend the same amount of time thinking about what their cash is doing while it idly sits in the bank.
For busy SME owners, dealing with the questions of what to do with the money may not feel like it’s worth the hassle. However, these assumptions may mean businesses are being penalised financially as they are missing out on additional interest that they could easily be earning over time.
Myth 1: You Need A Fixed Deposit To Earn Decent Interest
For a long time, this assumption made sense. Business accounts typically offered little interest, while fixed deposits were the standard option for businesses that wanted their cash to earn a return.
Today, however, businesses also have access to interest-bearing current accounts that allow operating cash to earn interest without having to move it into a separate product.
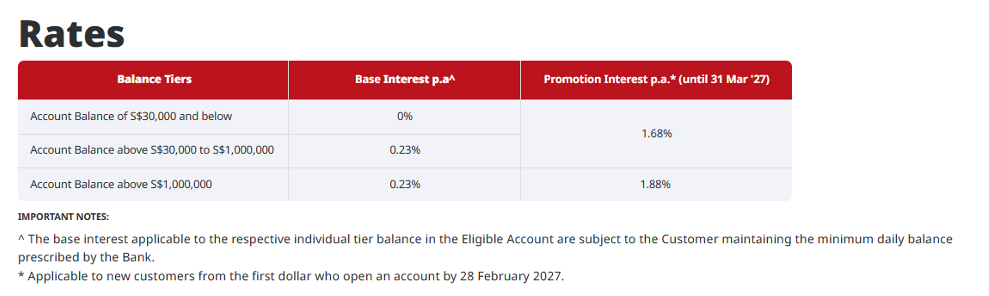
The CIMB SGD BusinessGo Current Account and CIMB USD Interest Plus Current Account, for example, currently offer 1.68%* p.a.up to first $1million and higher interest at 1.88%* p.a. for SGD and 2.88%* p.a. for USD for balances thereafter. There is no minimum balance^ required during the promotion period to start earning interest.
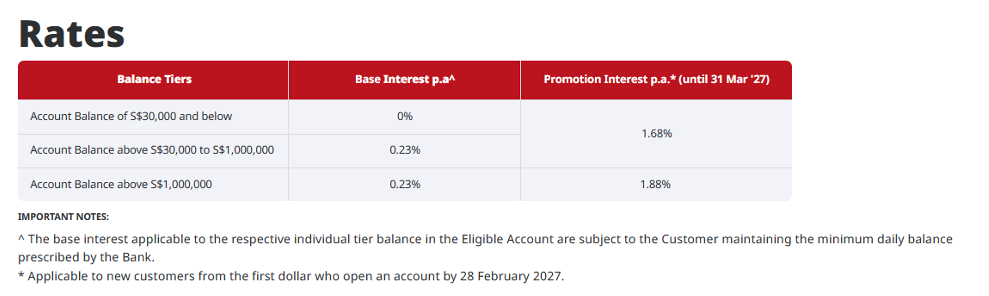
For an SME keeping US$300,000 in reserve, 1.68%* p.a. interest works out to be approximately US$420 per month, and the interest will be earned the earlier the account is opened and funded during the promotional period. That is a useful return on cash the business may already be holding for upcoming expenses or as a buffer. Unlike a fixed deposit, the money remains accessible, which can matter when you need the flexibility to respond quickly to payroll, supplier payments or other business needs.
Myth 2: Earning Interest Always Means Accepting A Lock-In Period
It is easy to assume that earning a higher return means giving something up, with access to your money being the obvious trade-off. Fixed deposits, for example, generally require you to commit your funds for a defined period.
But an interest-bearing current account works differently.
The CIMB SGD BusinessGo Current Account and CIMB USD Interest Plus Current Account work like a regular current account, so businesses can continue paying suppliers, receiving payments and managing day-to-day cash flow as usual. At the same time, the 1.68%* p.a. interest is earned based on the balance in the account, without requiring businesses to lock the money away for a fixed period.
This can be especially useful for SMEs with fluctuating or transitory cash. A payment received today may only sit in the account for a few days or weeks before it is used for payroll, supplier bills or other expenses. Even during that short window, the funds can still earn interest while remaining available for the business.
Myth 3: You Need To Move Your Money Around To Earn Interest
For SME owners, managing cash already involves keeping track of incoming payments, payroll, supplier bills and other operating expenses. Trying to earn more on that cash may therefore sound like another task to manage.
But earning interest does not necessarily require businesses to constantly monitor balances or move money around.
With an interest-bearing current account, funds that are already being kept for day-to-day business needs can continue earning interest while they remain in the account. This means an SME can use the same account to receive payments and meet operating expenses, without adding another cash-management step simply to earn interest.
Myth 4: Attractive Interest Rates Always Come With Complicated Conditions
It is understandable for business owners to be cautious when an account offers an attractive interest rate. Promotional rates can sometimes come with minimum balance requirements, transaction conditions, tiered structures or fees that chip away at the overall benefit.
That is why it is worth looking beyond the headline rate and understanding what is actually required to earn it.
For the CIMB SGD BusinessGo Current Account and CIMB USD Interest Plus Current Account, the 1.68%* p.a. interest rate applies up to first $1million and higher interest at 1.88%* p.a. for SGD and 2.88%* p.a. for USD for balances thereafter, with no minimum balance^ required during the promotion period to earn it. Businesses also do not need to lock in their funds or complete specific transactions to qualify for the stated rate.
| Open an account before 28 Feb 2027 to earn 1.68%* p.a. up to first $1million and higher interest at 1.88%* p.a. for SGD and 2.88%* p.a. for USD for balances thereafter and enjoy WAIVER* of minimum monthly balance until 31 March 2027. | |
| CIMB SGD BusinessGo Earn 1.68%* p.a up to first $1million and 1.88%* p.a. thereafter with no cap No monthly account fee**S$0 unlimited free local transactions – PayNow, FAST, GIRO No minimum balance^ requirement during the promotion period. (Usual: Minimum Monthly Average Balance S$30,000 otherwise a fee of S$88 applies per month.) Flat Telegraphic Transfer fee at S$18.88Get guaranteed1 best FX rates for cross border remittance transfers involving SGD to MYR and SGD to IDR. | CIMB USD Interest Plus Current Account Earn 1.68%* p.a up to first $1million and 2.88%* p.a. thereafter with no cap No monthly account fee**No minimum balance^ requirement during the promotion period. (Usual: Minimum Monthly Average Balance US$8,000, otherwise a fee of US$35 applies per month |
^At the Bank’s discretion, new account opening may be subjected to an initial minimum deposit requirement.
*Terms and conditions apply.
** Monthly account service fee, separate from the fall-below fee.
The fee waiver and no minimum balance requirement are also in effect until 31 March 2027, which helps keep the account simpler to maintain during this period.
For SME owners, the broader point is not to assume that a more attractive rate must come with more hoops to jump through. What matters is whether the account’s conditions, fees and access requirements fit the way your business actually manages cash.
A Banking Partner That Can Support Your Business Beyond The Account
Choosing a business bank is not just about where you keep your cash or the interest rate you can earn. For many SMEs, it can also be useful to consider whether the bank can support the business as its needs become more complex, particularly when it starts making cross-border payments, managing working capital or expanding into new markets.
That is where an account like the CIMB SGD BusinessGo Current Account and CIMB USD Interest Plus Current Account may be worth considering.
For businesses looking to keep things simple, the CIMB SGD BusinessGo Current Account and CIMB USD Interest Plus Current Account currently offers 1.68%* p.a. up to first $1million and higher interest at 1.88%* p.a. for SGD and 2.88%* p.a. for USD for balances thereafter, with no minimum balance^ required to earn interest. Funds remain available for everyday transactions, with no lock-in period or specific transaction requirements to qualify for the stated rate.
As always, business owners should compare the account’s full features, fees and terms with their own banking needs before deciding whether it is the right fit.
For business owners, this is like managing personal cash: you do not need to lock away money or chase the highest possible return. The aim is simply to make better use of cash during the periods when it is waiting to be spent.
About CIMB Singapore
CIMB is one of ASEAN’s leading banking groups, with a presence across eight ASEAN markets. In Singapore, its commercial banking business makes banking simple so that business clients can focus on growing their business. Each business client is supported by a dedicated Relationship Manager to support your business. Clients enjoy guaranteed2 competitive foreign exchange rates for SGD-MYR, SGD-IDR and SGD-THB transactions, as well as free intrabank transfers. Backed by in-house country expertise, CIMB offers tailored trade finance and working capital solutions to help businesses seize growth opportunities. This commitment to delivering exceptional banking solutions has earned the bank multiple industry awards, including “Singapore International Cash Management Bank of the Year” and “Best SME Business Current Account / Transaction Account” at the Asian Banking & Finance 2025 Awards. In addition, CIMB Singapore received “Best New SME Product of the Year”, “Outstanding SME Sustainable Finance Solution”, and “Outstanding Digital CX – SME Loans, Southeast Asia” at The Digital Banker 2026 Awards.
^ At the Bank’s discretion, new account opening may be subjected to an initial minimum deposit requirement.
*Terms and Conditions governing the NTB SGD and USD promotional interest/profit campaign apply. Click here for details.
1Terms and Conditions governing Best & Guaranteed rate. Click here for details.
Deposit Insurance Scheme
Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation, for up to S$100,000 in aggregate per depositor per Scheme member by law. Foreign currency deposits, dual currency investments, structured deposits and other investment products are not insured.
CIMB Bank Berhad, Singapore Branch 197201001799 (13491-P)


Branded Content
4 Business Banking Myths That Could Be Costing Your Company


