
This article is contributed by Vincent Ha, CEO of LytePay, a fintech company serving landlords and real estate agents in Singapore.
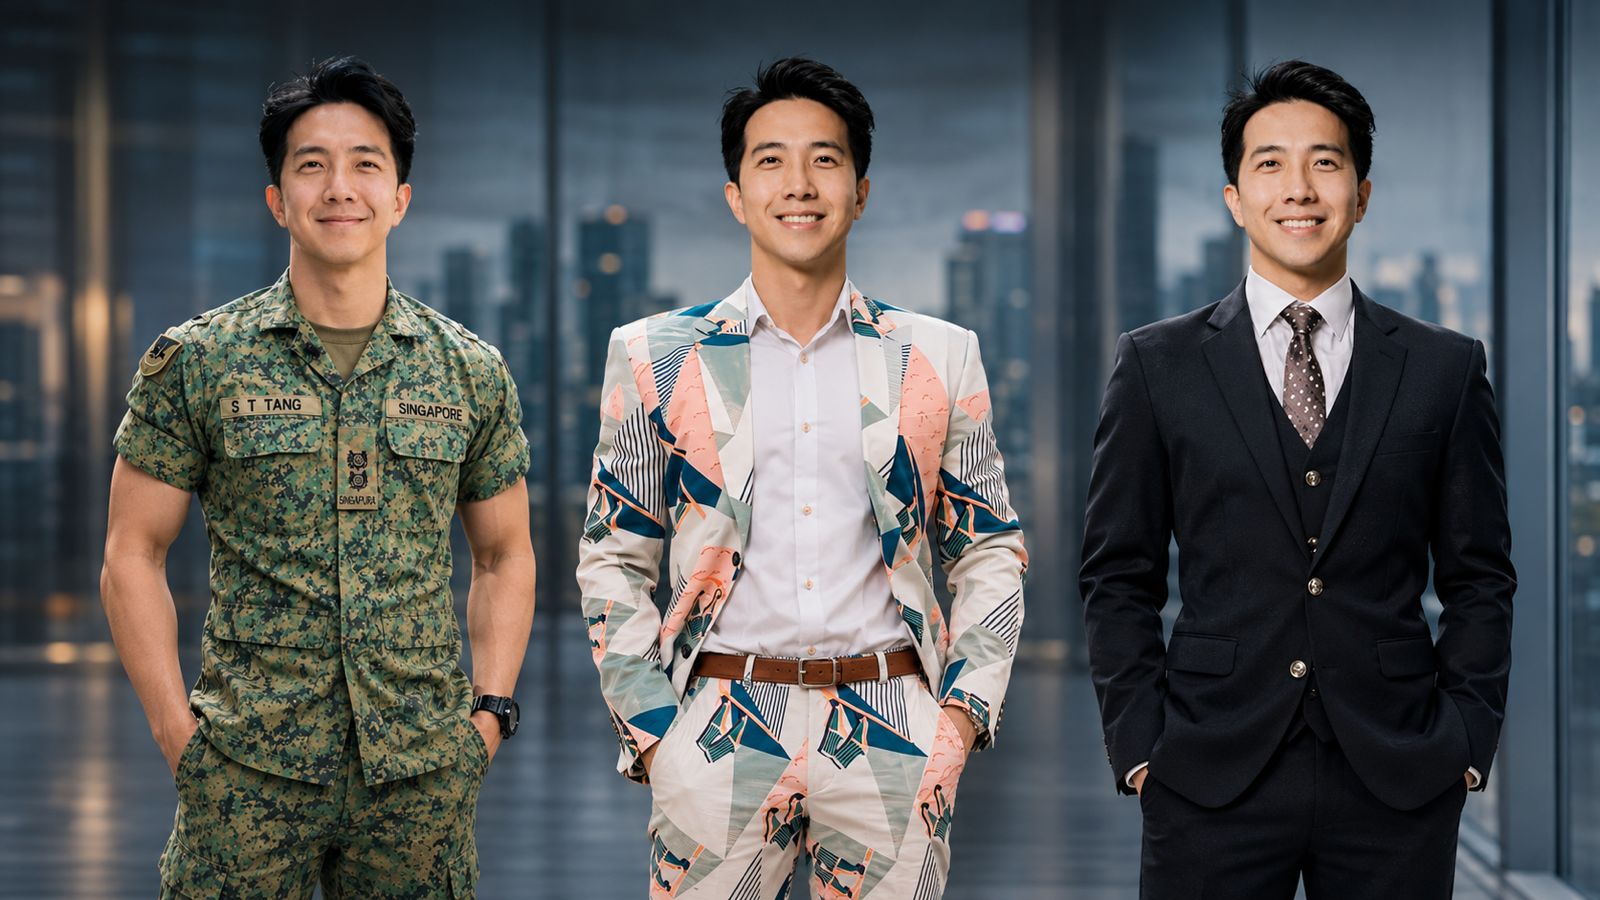
Before becoming a millionaire at PropNex in 2025, Marcus Tang spent seven years as an army officer, seven years as a financial adviser, and ventured into entrepreneurship. A tailoring business hit hard by COVID-19 and a US property investment that cost his family $400,000 taught him important lessons about money.
At Lyte, my team and I spend every day looking at how property agents manage their money. When I sat down with Marcus for an episode of Beyond The Commission, I wanted to understand what he had learnt from his experiences.
From Army Officer To Earning $500,000 As A Financial Adviser
Marcus’s father was an army regular. Growing up listening to his father’s stories, Marcus decided at 15, while still in Secondary 3, that he would sign on as an officer. He went on to serve for seven years before following the example of a former senior officer who had joined AIA.
The army taught Marcus to be disciplined even as his working arrangements changed. “When you become a financial adviser, you suddenly have freedom. You can do anything you want. But freedom can be quite chaotic. The army taught me routines and habits that made my freedom more structured.”
Marcus joined AIA at 26 and was named top rookie, earning about $500,000 in his first year. He acknowledges that his experience was unusual: many advisers take years to build their income through commissions from regular-premium policies. Marcus had a head start by serving high-net-worth clients.
When he moved into leadership, his annual income fell to between $200,000 and $300,000. Training other advisers left him with less time to serve his own clients. It took him a few years to rebuild his income, which peaked around his fifth year in the business.
Financial advisers and property agents share a common challenge: unpredictable income. Earning half as much one year can be challenging if your mortgage, car loan and other commitments remain unchanged. Those who are self-employed need to plan for such periods even when business is going well.
Read Also: How Much Can You Earn As A Property Agent In Singapore?
A $700,000 Lesson On The Importance Of Insurance
In 2009, Marcus’s father was diagnosed with stage four lung cancer, which subsequently spread to his spine and brain. Over three years of treatment, the family incurred close to $700,000 in medical bills. According to Marcus, his father did not have insurance coverage for these expenses.
“When my friends could buy a car and have a good time, all my money had to go towards repayment. My brother’s too, and my mother’s.”
That experience shaped his belief that insurance protection, investments and property ownership should go hand in hand. Without adequate protection, a serious illness can undo years of financial progress for an entire family.
Why Property & Financial Planning Should Go Hand In Hand
Financial advisers and property agents often work with the same pool of money. While a financial adviser may recommend putting additional savings into insurance or investments, a property agent may suggest upgrading to another property.
“It’s like a tug of war over the same pot,” Marcus says. “The person who loses is the consumer. It just comes down to who is the better salesperson.”
Having worked in both industries, Marcus believes property agents and financial advisers should work together. While asset progression can help Singaporeans build wealth, it should not come at the expense of adequate insurance protection and retirement planning.
Marcus asks clients to place themselves on a scale of zero to 10, where one end represents buying purely for investment and the other represents buying entirely for their own stay. This helps him understand their priorities before recommending a property, and is a useful question we can ask ourselves before our next purchase.
How A Millionaire Property Agent Allocates His Income
I asked Marcus to imagine a month in which he earns $100,000 and explain how he would allocate his income. He spends roughly $2,000 a month on business production costs such as marketing. Another $8,000 to $10,000 goes towards investments in index funds and bonds, with the remaining money allocated to property, living expenses and his family.
Property is his primary means of growing wealth, partly because he is comfortable with Singapore’s banking system and property lending regulations. While leverage allows him to purchase higher-value assets, it can also magnify losses. His other investments provide diversification, while insurance provides financial protection.
His Best & Worst Property Investments
During his time as a financial adviser, Marcus invested in a US property development that cost him and his mother about $400,000. According to Marcus, legal proceedings remain ongoing. His tailoring business was another costly experience when COVID-19 ate into his savings and early earnings as a property agent.
“My entrepreneur journey taught me humility. When I came out of it, I became quite conservative with the way I manage my money.”
His most successful investment was much closer to home. After his first year as a financial adviser, Marcus bought a property in Hillview before the new MRT station and surrounding developments were completed. The profits became the capital for subsequent property investments. Unlike his US investment, this was an asset in an area he understood and could monitor himself.
Three Common Financial Mistakes Property Agents Make
Marcus cautions against buying an expensive car too early in one’s career. After receiving their first substantial commission, some agents may commit to a lifestyle that requires them to continue earning at the same level. Regular spending on luxury goods can similarly leave them with insufficient savings during quieter months.
The third is not investing enough in the business. Beyond paying for property listing portals, Marcus believes agents should consider investing in administrative, marketing and operational support as their businesses grow. Doing everything themselves limits how much business they can take on.
How Marcus Invests In His Business To Buy Back Time
In his early days as a property agent, Marcus handled everything himself, from rental transactions and HDB flats to paperwork and weekend property viewings. While he was constantly busy, he had little time to think about growing his business.
Today, he co-brokes with agents specialising in HDB, industrial and commercial properties, sharing commissions. He focuses on generating leads and handling new launches, with support from a shared personal assistant and an operations manager.
“I decided I didn’t want to spend every weekend at somebody’s house doing a showing. It was so liberating. Suddenly I had the clarity to think: I can do collaborations, I can do partnerships, I can talk to business owners.”
With more time available, Marcus started meeting directors of financial advisory agencies, potentially reaching a larger network of advisers and their clients. For him, sharing commissions and paying for support staff are investments that allow him to spend more time growing his business.
Managing Cash Flow When Property Commissions Take Months To Arrive
Property agents can wait months between closing a deal and receiving their commission. Marcus experienced this during his first year as an agent, when his savings were already depleted by his previous business ventures. He was reluctant to commit money to marketing activities such as paid search advertisements.
Today, Marcus uses LytePay to access eligible commissions ahead of their scheduled payment. He recently took a sizeable commission advance, even though he had not yet deployed the funds.
When I asked why, he explained, “Sometimes an opportunity doesn’t wait for you. I’d rather have the money with me now, so that whenever an opportunity comes, I can act.”
Marcus is looking for business opportunities, including ways to generate more leads. Unlike credit facilities that typically charge interest on outstanding balances, LytePay charges a one-time processing fee. For Marcus, the consideration is whether early access to his commissions can generate enough additional returns to justify the fee. Agents should weigh this cost, especially if they have no immediate use for the money.
Defining Financial Success Beyond Earning A Million Dollars
Having previously chased income, status and awards, Marcus now wants more time for his wife, three young children and mother, including the flexibility to take three months off for a family holiday.
His goal is to build a business that generates around $2 million a year without requiring all his time. He would continue doing what he enjoys, such as coaching his team and building relationships with clients, without the constant financial pressure.
“I’ve been running on hyperdrive for the past 20 years of my life. It’s time to focus on things that are closer to heart.”
For him, earning more money today is ultimately about having greater control over how he spends his time.
One Last Thing: How To Choose A Good Suit
I could not let a former tailoring entrepreneur leave without asking him for some advice. Marcus recommends prioritising fit over fabric labels, choosing colours that complement your skin tone and wearing patterns that suit your personality. If you are unsure about bold prints, stick to classics such as checks or stripes.
Marcus Tang (CEA Registration No. R070688H) is a property agent with PropNex. This article is based on an episode of Beyond The Commission, a podcast by Lyte featuring Singapore’s top property agents. Vincent Ha is the CEO of Lyte, which operates LytePay. This article should not be relied upon as financial advice.


Bonds and Fixed Income
6 Investments In Singapore That Provide Guaranteed Principal And Returns


