
This article is sponsored by Bigfundr. All views expressed in this article are the independent opinion of DollarsAndSense.sg based on our research, are purely for informational purposes, and should not be relied upon as financial advice. DollarsAndSense.sg is not liable for any financial losses that may arise from any transactions, and readers are encouraged to do their own due diligence. You can view our full editorial policy here. This advertisement has not been reviewed by the Monetary Authority of Singapore.
For many Singapore investors, T-bills, Singapore Savings Bonds (SSBs) and fixed deposits are some of the familiar starting points when we want to build an income portfolio. These instruments allow us to earn interest on money we have set aside, whether we are saving for an upcoming expense or putting our longer-term savings to work.
However, the returns generated by some of these instruments may leave some investors wanting more. With the recent six-month T-bill auction on 22 October 2026, the cut-off yield was 1.95% per annum. This means S$10,000 invested for six months would earn roughly just S$98.
For investors seeking higher returns without assuming disproportionate risk, the question increasingly becomes where to find attractive risk-adjusted returns beyond traditional equities. Against a backdrop of geopolitical uncertainty and volatile equity markets, investors may be looking for a middle ground between higher-risk growth assets and lower-returning investments focused primarily on capital preservation, creating a role for alternative income strategies that seek to balance return potential, income visibility and downside risk.
Investing In Private Credit
One option for Singapore investors is to consider investing in private credit. In simple terms, private credit involves lending money to businesses or other borrowers through privately arranged loans in exchange for interest payments.
Businesses borrow for different reasons, such as funding their operations, expanding into new markets or financing a property development. While banks remain a traditional source of finance, non-bank lenders can provide more tailored and flexible funding structures designed around the particular needs, cash flows and timelines of the underlying project. This creates opportunities for private-credit investors to provide capital where a more bespoke financing solution is required.
BigFundr is a Singapore-based platform that connects investors with private credit opportunities. As an MAS-licensed capital markets services provider, BigFundr offers access to short-term, real estate-backed fixed-income investments linked to property financing in Australia. Rather than purchasing property directly, investors can invest in loans that finance property projects and earn interest over the agreed investment tenure.
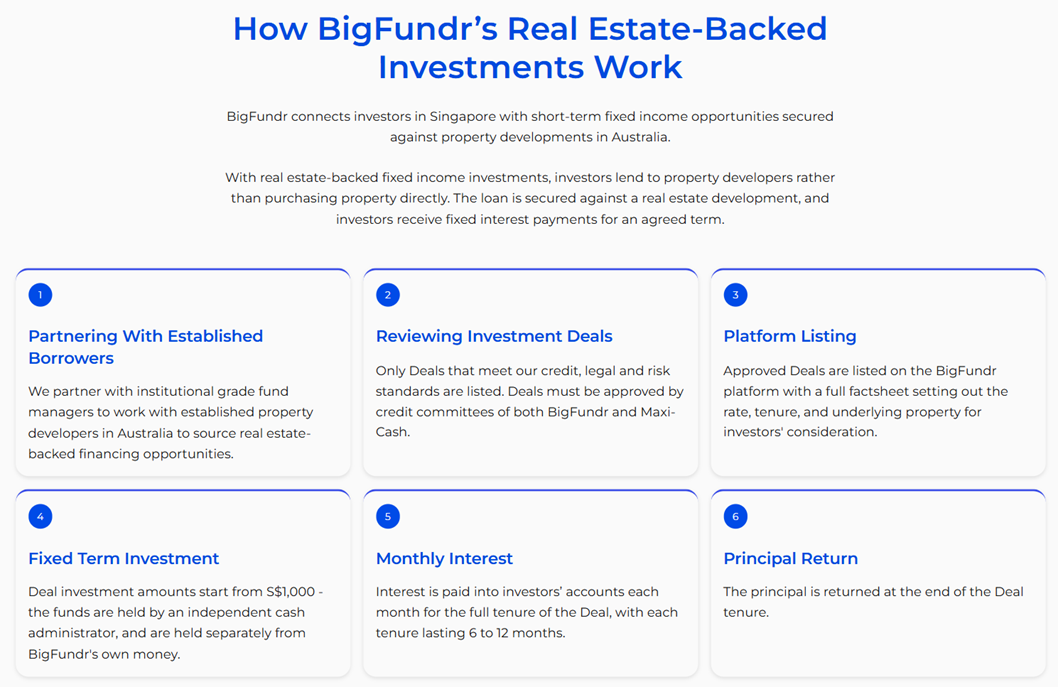
Investments start from S$1,000, with Deal tenures typically ranging up to 12 months. Interest is paid monthly, while the principal is due for repayment at the end of the investment tenure.
Each Deal has a factsheet detailing the interest rate, tenure and underlying property collateral, allowing investors to assess the key terms and risks before deciding whether to invest.
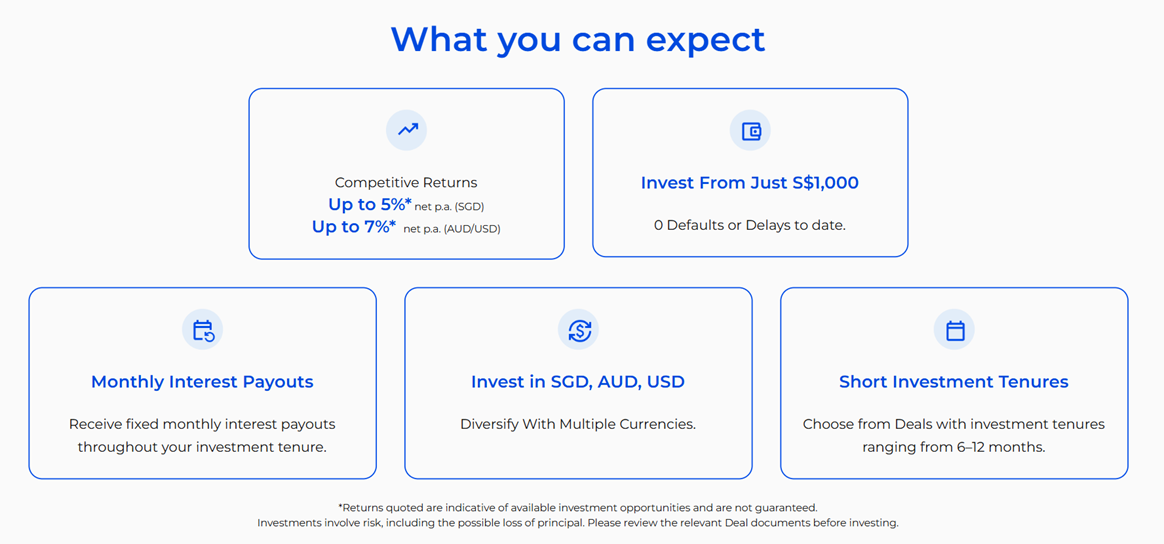
For investors already holding T-bills, SSBs and fixed deposits, BigFundr could offer an additional source of interest income with potentially higher returns, though real estate debt investments come with borrower default, loss of principal and liquidity risks. BigFundr mitigates these risks with multiple safeguards as highlighted below.
The monthly interest payments can serve as passive income to supplement other earnings or help cover expenses. Alternatively, investors can reinvest the interest into other available deals on the platform, alongside additional funds, to build their income portfolio over time.
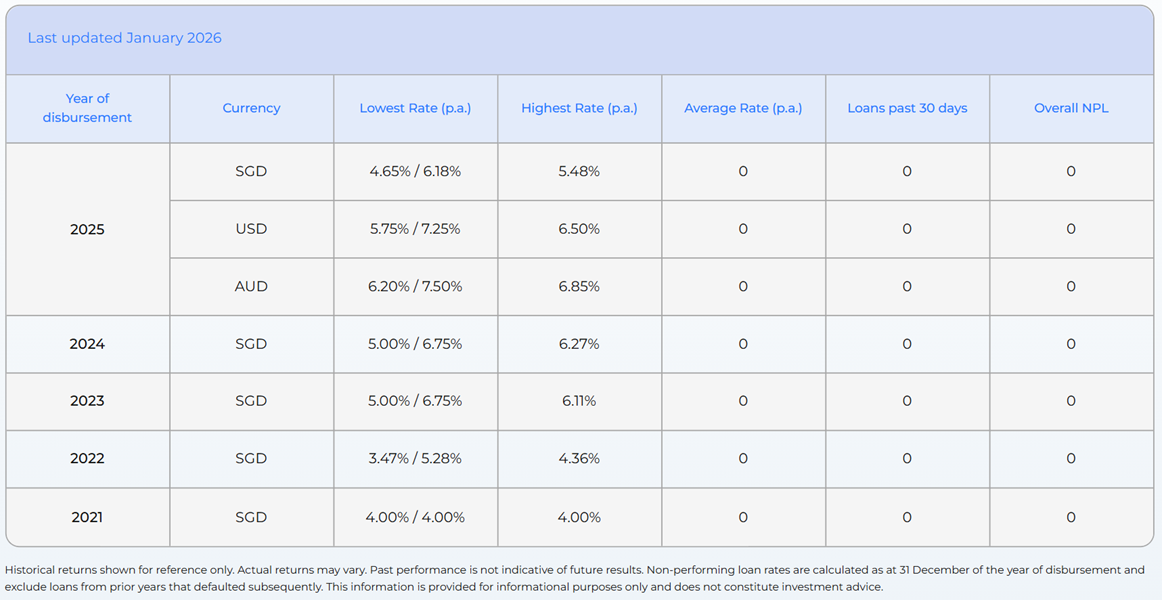
Investors can also spread their investment across multiple BigFundr Deals to reduce reliance on a single loan. Choosing Deals involving different borrowers, projects and locations can provide some diversification.
Loan Deals Listed On Bigfundr Are Secured Against Property
BigFundr’s loans are secured against property, typically through a first legal charge¹ over the underlying real estate. If a borrower defaults, this gives BigFundr priority in seeking repayment from the proceeds of the property.
BigFundr also typically caps the loan-to-value (LTV) ratio at 70%, meaning a property valued at S$10 million would support a loan of no more than S$7 million, providing an initial 30% buffer against a fall in property value before the loan principal is reached.
Before being listed, each Deal is screened for borrower quality, asset value (independently assessed by a licensed valuer), risk and project fundamentals. The Deal must be approved by both credit committees of BigFundr and Maxi-Cash². Property valuations, legal title checks and security documentation need to be completed and are conducted by a large law firm. Safeguards also typically include personal and corporate guarantees, providing another avenue to recover any shortfall, subject to the guarantors’ ability to pay.
Deciding Which Money You Can Commit
Consider an investor who has S$100,000 in savings. The investor set aside S$20,000 for emergencies, S$30,000 for a renovation next year and another S$50,000 for longer-term investments.
The emergency savings need to remain readily accessible, so the investor would likely keep them in a savings account. The renovation funds also have a clear purpose and deadline so S$30,000 could be set aside in a fixed deposit.
For the remaining S$50,000, the investor could consider putting part of the money into BigFundr Deals. Before committing, they would review each Deal’s factsheet and assess whether they can accept the loan tenure, possible repayment delays and potential losses. They could also spread their investment across different Deals to reduce reliance on a single loan, while using the monthly interest to supplement their income or build towards future investments.
The amount to invest will depend on their financial commitments, existing portfolio and comfort with risk. For those considering BigFundr, reviewing the available Deals is a starting point. The decision comes down to whether the potential returns, investment terms and risks suit the money they can commit.
Celebrate the Christmas Season with Higher Returns
For first-time investors, enjoy an extra 0.1% net p.a.³ on your first Deal with the promo code FIRST2026. Each Deal will be funded on a first-come, first-served basis. This promo code is valid until 31 December 2026 and cannot be used in conjunction with any other codes or promotions.
Sign up for a BigFundr account to start earning your interest.
¹ These safeguards are intended to strengthen the investment structure but do not eliminate investment risk.
² Maxi-Cash Capital Management Pte Ltd, a wholly owned subsidiary of Aspial Lifestyle Limited, an SGX-listed company.
³ Terms and conditions apply. BigFundr is licensed by the Monetary Authority of Singapore (MAS) and operates under the Capital Markets Services Licence (CMS Licence 101098). This advertisement has not been reviewed by the Monetary Authority of Singapore.


Bonds and Fixed Income
6 Investments In Singapore That Provide Guaranteed Principal And Returns

Health Insurance
5 Questions To Ask Before Dropping Your Integrated Shield Plan Rider


Bonds and Fixed Income
6 Investments In Singapore That Provide Guaranteed Principal And Returns


