
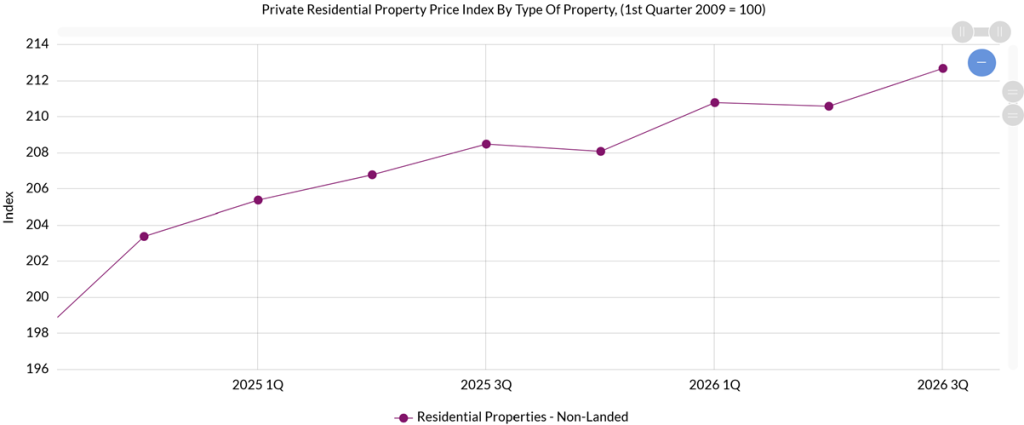
Unlike resale HDB flat prices, which fell for three consecutive quarters in 2026, Singapore’s private property market remains strong. According to the latest statistics from the Urban Redevelopment Authority (URA), prices of private residential properties increased by 1.4% in Q3 2026. This was driven mainly by landed properties, which rose 2.9%, while non-landed properties, including apartments and condominiums, rose 1%.
The private residential property price index in Q3 2026 rose to 222.5, the eighth consecutive quarter of price increases, despite the challenging global economic environment.
Source: Singapore Department of Statistics
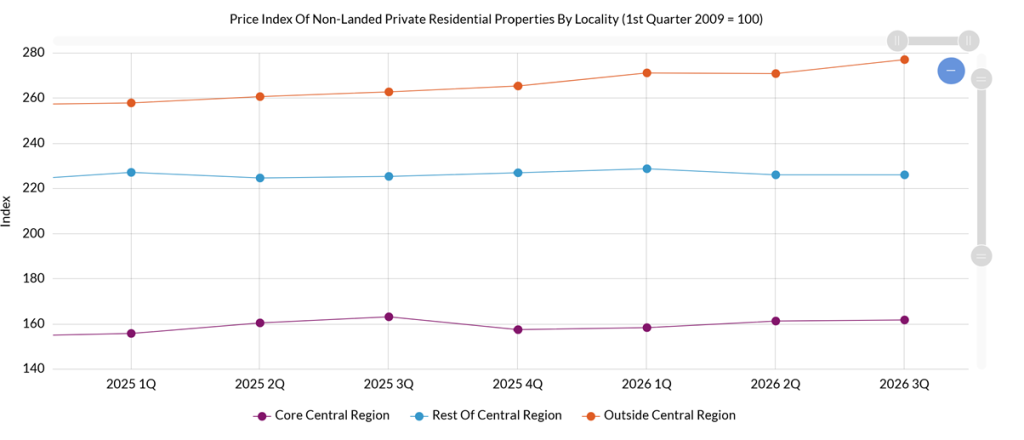
This price growth does not affect every part of Singapore equally. If we examine how the condominium market has performed since the end of 2025, the strongest price growth was not in the Core Central Region (CCR) or even the Rest of Central Region (RCR), but in the suburban Outside Central Region (OCR).
Source: Singapore Department of Statistics
Read Also: Price Guide To Landed Properties In Singapore
The OCR Has Been The Clear Performer Over The Past Year
The price index for the CCR rose about 2.7% since Q4 2025, while the RCR price index remained relatively stagnant. The biggest performer has been the OCR price index, which grew by 4.4%.
The following information is taken from URA’s quarterly data for non-landed private residential properties over the past year.
| Quarter | CCR | RCR | OCR |
| Q4 2025 | -3.5% | +0.7% | +1.0% |
| Q1 2026 | +0.6% | +0.8% | +2.2% |
| Q2 2026 | +1.8% | -1.2% | -0.1% |
| Q3 2026 | +0.3% | 0.0% | +2.3% |
The CCR entered 2026 on the back of a sharp 3.5% decline in Q4 2025 and subsequently staged a gradual recovery. The RCR went back and forth between gains and declines before stagnating in Q3 2026.
In contrast, the OCR recorded the strongest quarterly performance in three of the four quarters under review, with prices increasing by a year-long high of 2.3% in Q3 2026. This is relatively modest, compared to the 3.2% price growth in 2025 and 3.7% price growth.
This Does Not Mean That The CCR Performed Poorly
The CCR remains Singapore’s most prestigious private residential segment and continues to attract affluent local purchasers seeking premium locations.
New luxury condos in the CCR, like 21 Anderson, Watten House and Amberwood at Holland commanded a median price of $3,059 psf, while resale condos sold at a median price of $2,169 psf.
The 3.5% correction recorded in Q4 2025 left the CCR with significant ground to recover, although prices eventually rose in the first three quarters of 2026.
Read Also: Guide To Condo Rental Yields In Singapore [2026 Edition]
The RCR Is The Only Region Where Price Growth Has Stagnated
This region, which is supposed to bridge the luxury residences of the Core Central Region and the mass-market developments in the OCR, has seen growth flatten over the past year.
Despite the popularity of new launches such as Zyon Grand, which sold 84% of units at $3,050 psf a year ago, the region’s relative lack of new launches may have affected price growth. Resale condos sold at a median price of $2,103 psf, not that far removed from CCR prices.
In fact, the condo prices in the RCR dipped over the past year – prices are slightly lower than where they were at the start of 2026.
Expect an upturn in 4Q 2026, however, with the recent launch of Thomson Reserve, the highly anticipated development at Bright Hill Drive. Homebuyers bought 90% of units at launch at an average $2,900 psf.
The OCR’s Relative Affordability Continues To Shape Buyer Behaviour
Despite rising condominium prices, the OCR continues to offer a more accessible entry point into the private housing market than most city-centre or city-fringe alternatives. For many buyers, especially HDB upgraders, a condo unit in the OCR is a very viable option.
Recent launches at Tengah Garden Residences, Pinery Residences and Lentor Garden Residences have all contributed to a median $2,436 psf in the past year. Resale condos in the RCR were priced at a very modest $1,548 psf.
As long as suburban developments continue to offer comparatively larger homes, newer projects and a lower overall purchase quantum, they will remain attractive to a significant proportion of homebuyers.
Read Also: Complete Guide To Buying Landed Property In Singapore


Bonds and Fixed Income
6 Investments In Singapore That Provide Guaranteed Principal And Returns

Health Insurance
5 Questions To Ask Before Dropping Your Integrated Shield Plan Rider


Bonds and Fixed Income
6 Investments In Singapore That Provide Guaranteed Principal And Returns


